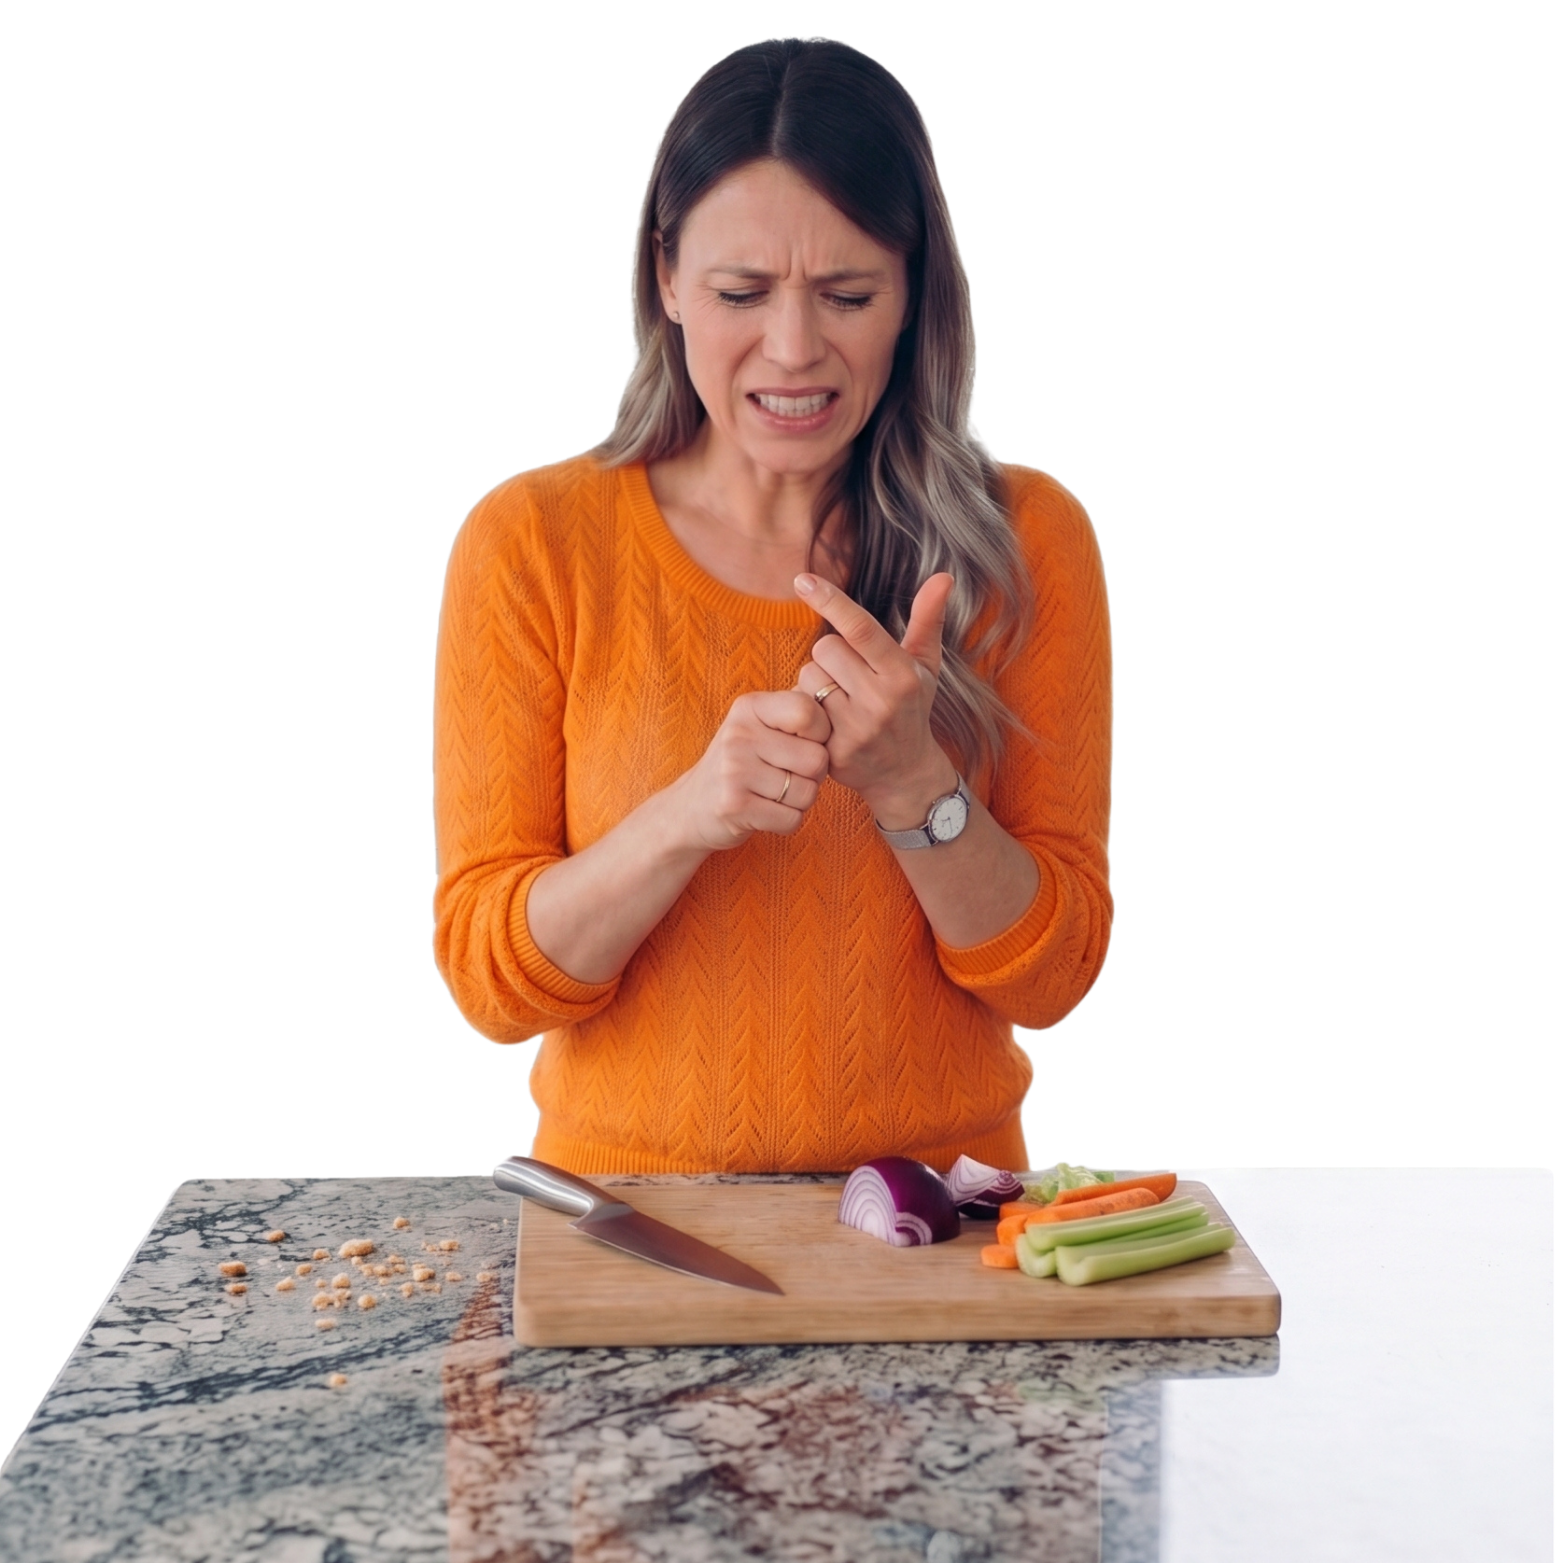
Most accidents aren’t catastrophes. That’s the catch
A health plan with a high deductible does its real work in a disaster. A broken wrist, a deep cut, a bad landing: those bills land squarely inside the deductible, and you pay them out of pocket. Accident insurance covers exactly that zone: fixed cash amounts per covered treatment, from day one, whether or not your health plan has paid a cent.
The trampoline party
ER, X-ray, cast, follow-up: a routine kid fracture, handled in one afternoon and billed entirely inside a typical deductible.
The rec-league ankle
Urgent care, imaging, a walking boot, then physical therapy. Nobody’s emergency, just weeks of visits that add up.
The garage ladder
Eight stitches and a tetanus shot at urgent care. Small enough to shrug off, big enough to notice on a bank statement.
No waiting period
Accident benefits start the day your policy does. No enrollment window, nothing to accrue.
Hospital admission
Generally, though not always, this is where the benefit pays its full amount. An inpatient stay triggers the largest line on the schedule.
Follow-ups count too
Urgent care, therapy, and checkup visits within your policy’s window are covered categories on most plans.
Most eligible expenses must occur within the policy’s stated window after the accident. Your benefit schedule lists the exact amount per category.
A benefit you can size to your deductible
Benefit levels are set when you enroll, so the payout can be structured as a hedge against your deductible. If something beyond a routine visit arises, and the treatment is a covered service under your plan, the stated amounts pay in the zone your health plan makes you cover first.
- Size the benefit level to mirror your deductible when you enroll
- Covered treatments pay their stated amounts, whether or not your health plan has paid yet
- Benefits are paid to you, so the money lands exactly where the gap is
Illustrative. Benefit levels and covered services vary by plan and state.
Frequently asked questions
 Answers by our licensed team Reviewed for accuracy Updated September 1, 2026