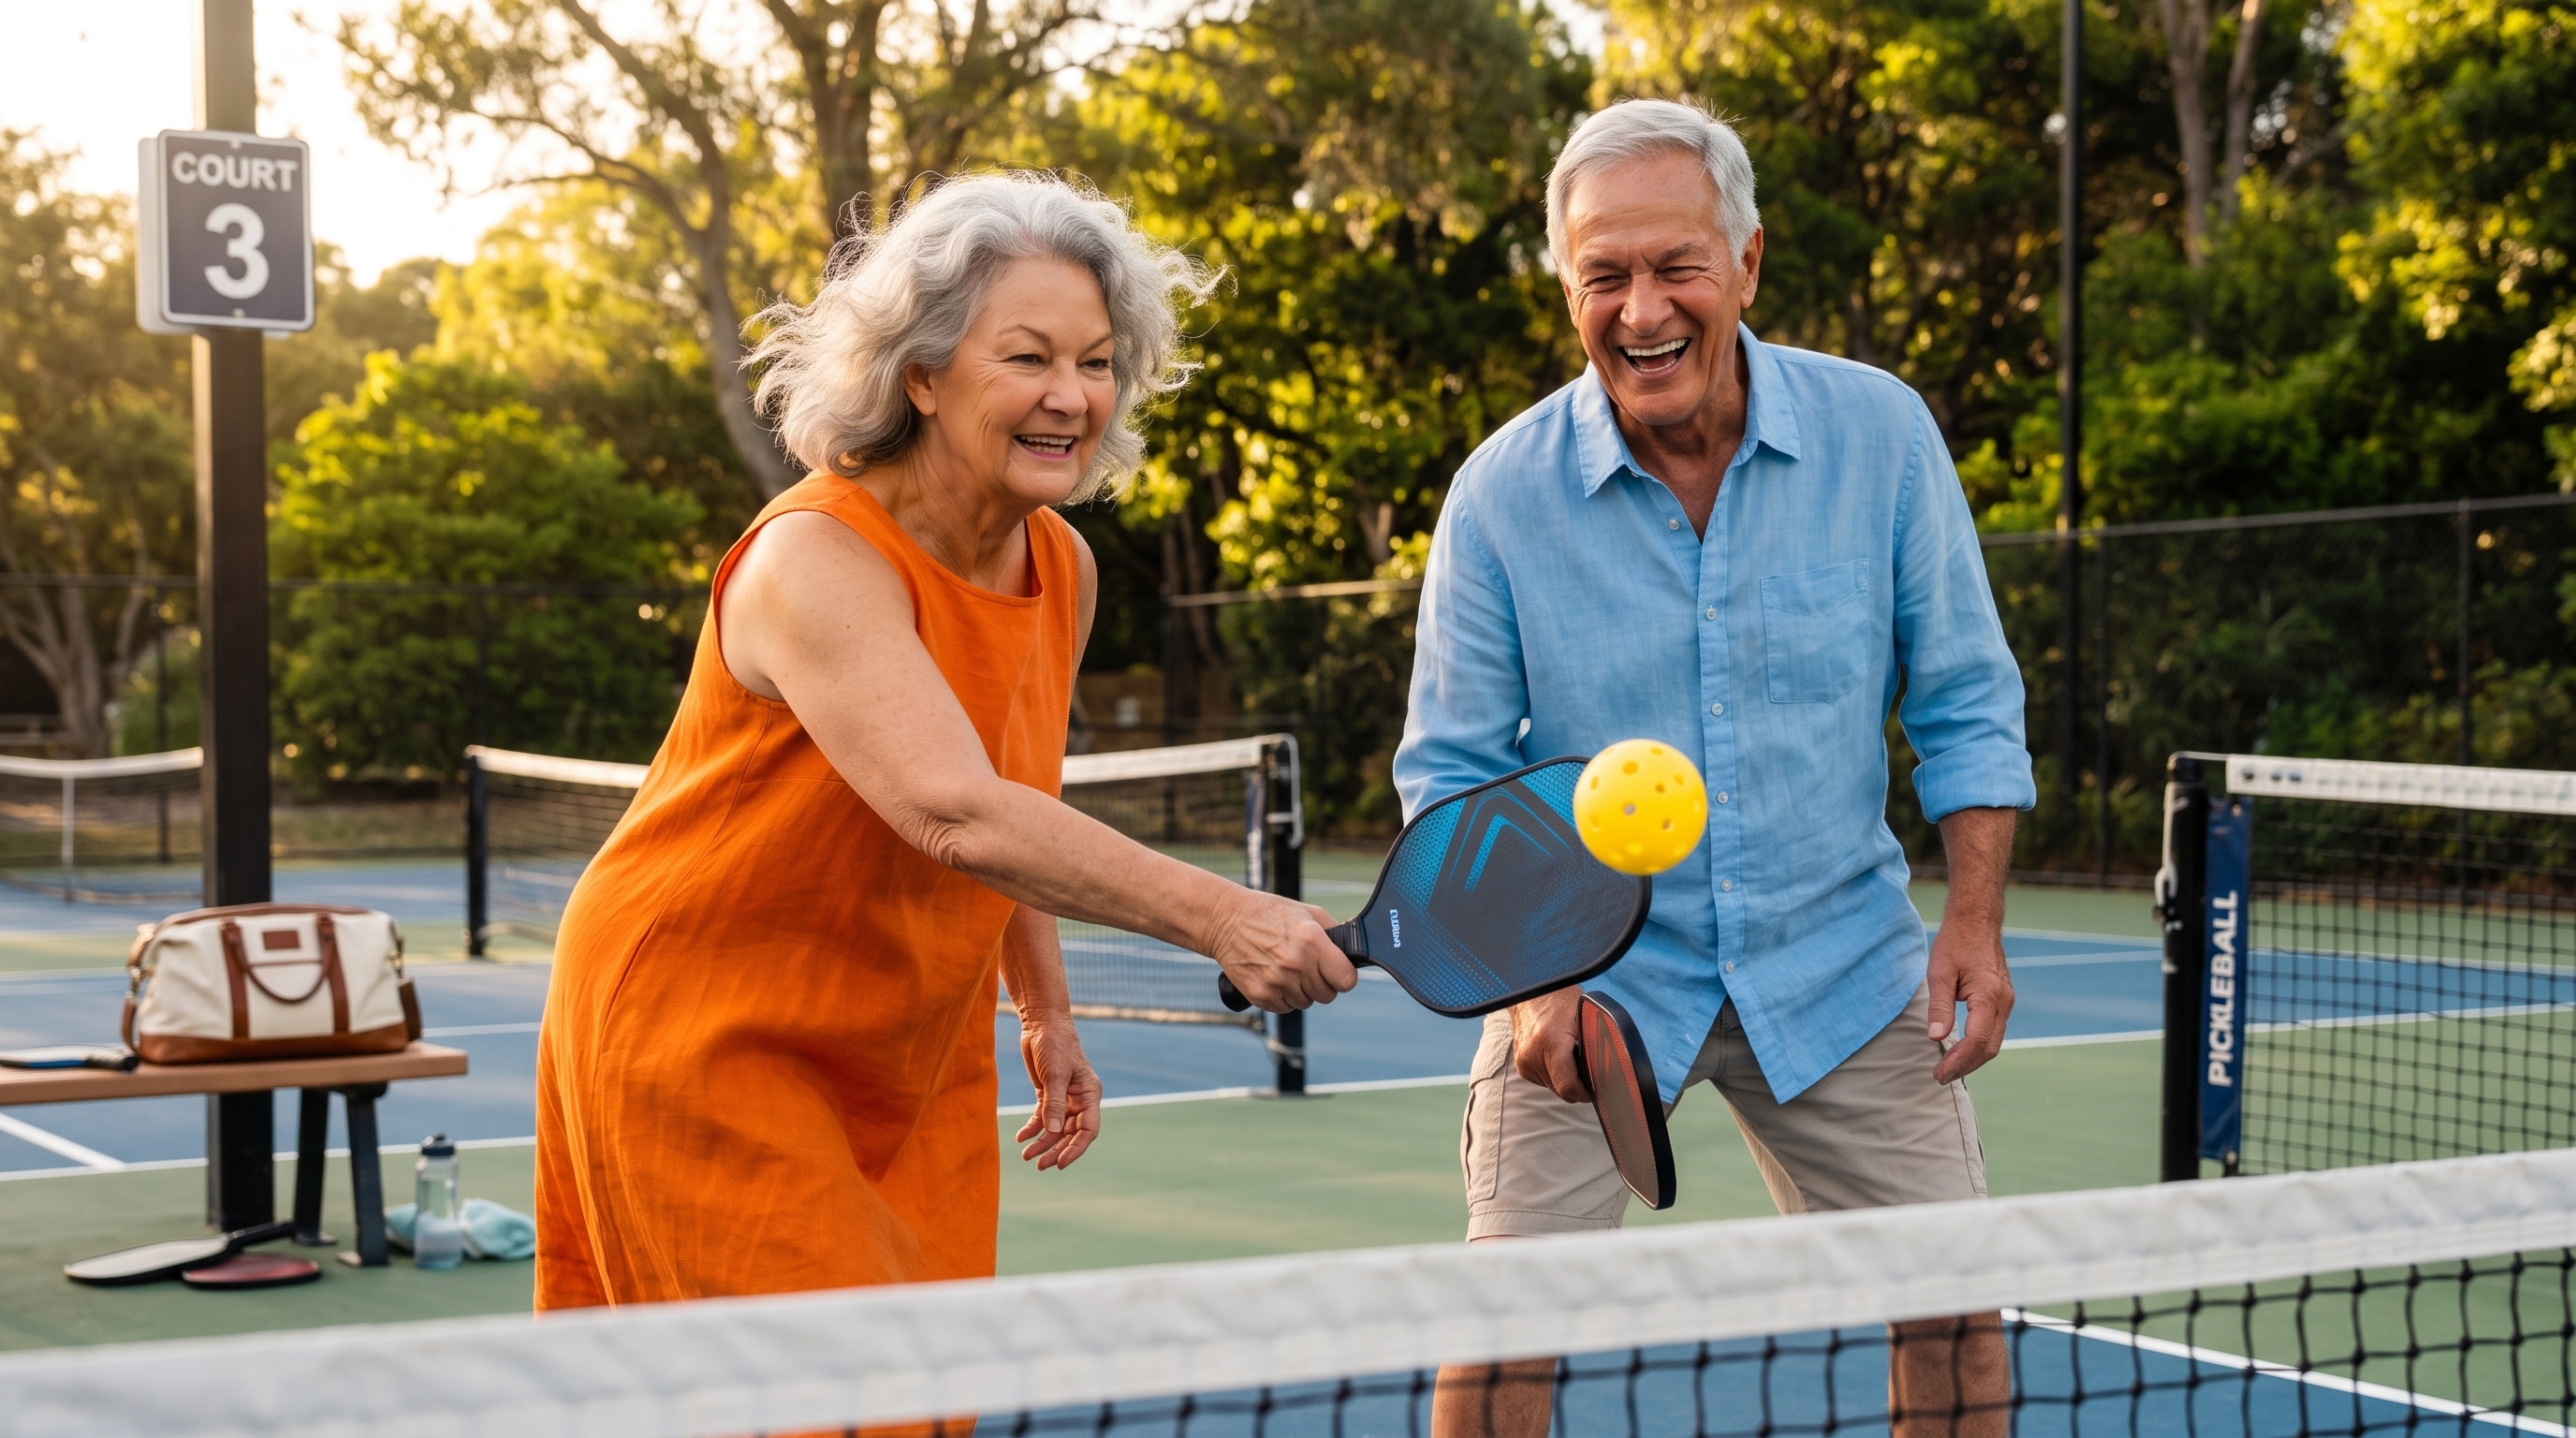
Is a multi-year bridge the right tool for you?
The common thread: healthy today, needing one to three years of private coverage, and not counting on a subsidy.
Self-employed, without group coverage
Freelancers and small-business owners who earn too much for subsidies and want a multi-year private plan at a workable premium.
Early retirees bridging to Medicare
Retiring at 62 or 63? A ~36-month runway can carry you to 65 with one application, no annual re-shopping in between.
Healthy households leaving employer coverage
Families in good health who want coverage that outlasts a single short-term policy, without betting on next year’s application.
Multi-year terms
In states that allow it, consecutive terms can extend coverage well beyond one year.
Underwritten, not ACA
Medically underwritten and not minimum essential coverage — the tradeoff for the price.
State rules govern
Availability and maximum duration are set by state law; some depend on current federal policy.
Frequently asked questions
 Answers by our licensed team Reviewed for accuracy Updated July 3, 2026